Understanding the different methods of buying HDB flats
Each method caters to different needs and priorities:
Build-To-Order (BTO): BTO flats are new flats offered by HDB for purchase before they are constructed. This option allows buyers to customize their flats and often comes with a fresh 99-year lease. However, it involves a waiting period for construction to be completed.
Sales of Balance Flats (SBF): SBF exercises offer flats that were not sold during previous BTO sales or have been repurchased by HDB. This can be a good option for those who want a shorter waiting time than BTO but still desire a relatively new flat.
Open Booking: For buyers seeking immediate occupancy, Open Booking allows direct application and booking of available unsold flats. This option typically offers the shortest waiting time to key collection.
Buying a new flat: Step-by-step proces
Step 1: Check eligibility
The first and most crucial step in purchasing an HDB flat is to determine your eligibility. This is done by applying for an HDB Flat Eligibility (HFE) letter. The HFE letter is an official document from HDB that assesses your eligibility to:
Purchase a new HDB flat (BTO, SBF, or Open Booking)
Apply for housing grants, such as the Enhanced CPF Housing Grant (EHG)
Obtain a housing loan from HDB or a bank
The HFE letter considers several factors, including your citizenship, age, income, and property ownership history. It also helps you to understand your financial capacity and work out your housing budget, ensuring you purchase a flat that you can afford.
Step 2: Apply online during the sales launch
BTO (Build-To-Order): Think of these as brand-new flats, built from scratch. HDB launches these projects a few times a year in different locations. The cool thing is you get a fresh 99-year lease, and sometimes you can even choose some of the finishes. The catch? You’ll have to wait a few years for them to be built.
SBF (Sales of Balance Flats): These are flats that didn’t get sold in previous BTO sales, or that HDB has bought back. So, they’re not brand new, but they’re usually newer than resale flats, and the waiting time can be shorter than BTO. HDB also holds SBF exercises a few times a year.
Open Booking: If you’re in a hurry to move, this is the quickest option. HDB lists flats that are available right now, and you can book them directly. It’s first-come, first-served, though!
To find out about upcoming BTO and SBF launches, you’ll want to keep an eye on the official HDB website – that’s where all the official info is. When you’re browsing, think about where you want to live, how much space you need, and of course, how much you can afford.
Buying a flat is a huge financial commitment, so it’s really crucial to get your ducks in a row. Here’s what you need to think about:
Downpayment: This is the initial amount you need to pay upfront. The exact amount depends on whether you’re taking a loan from HDB or a bank.
Mortgage: Unless you’re paying for the whole flat in cash, you’ll need a home loan. You’ll want to figure out how much you can borrow and how much your monthly repayments will be.
Other costs: Don’t forget that there are other expenses involved, like Buyer’s Stamp Duty (BSD) – a tax you pay to the government – legal fees, and maybe even renovation costs if you’re not a fan of the standard fittings.
It’s worth checking out the grants you might be eligible for, like the Enhanced CPF Housing Grant (EHG). These grants can really make a difference and lighten the financial load.
Step 3: Book a flat
After deciding on a flat type and development that suits your needs, the next step is to apply for it during the designated sales launch period (for BTO and SBF).
Applications are submitted online through the official HDB website. For BTO and SBF, after the application period closes, HDB will conduct a ballot to determine the queue order of applicants. Applicants will receive ballot results, indicating their queue number. This number determines the order in which they can select a flat.
Step 4: Secure your flat with the Option Fee
If your queue number is favourable in a BTO or SBF exercise, or if you’re booking an open booking flat, you will proceed to book a flat. When booking a flat, you’ll need to pay an Option Fee.
The Option Fee secures your chosen flat temporarily, taking it off the market while you proceed with the purchase. The Option Fee will form part of the required downpayment for the flat.
Step 5: Sign the agreement for lease and make the downpayment
The next crucial step is signing the Agreement for Lease with HDB. This is a legal document that formalizes your purchase of the flat. This document outlines the terms and conditions of your flat purchase. Ensure you understand all the clauses before signing.
You’ll also need to pay the downpayment when you sign the Agreement for Lease. The downpayment amount varies depending on whether you take an HDB loan or a bank loan:
If you’ve taken an HDB Loan:
The downpayment can be paid using a combination of your CPF Ordinary Account (CPF OA) savings and cash.
HDB sets the specific downpayment percentages, which may vary depending on prevailing policies.
There may be a minimum cash component required.
If you’re financing through a bank loan:
Bank loan downpayment requirements differ from HDB loan requirements.
Banks typically require a larger cash component for the downpayment.
The Loan-to-Value (LTV) ratio also affects the cash/CPF allocation.
Remember: If you are financing your flat purchase with a bank loan, it is essential to secure a valid Letter of Offer from the bank before signing the Agreement for Lease. This letter confirms the bank’s commitment to provide the loan.
Step 6: Key collection and final payment
The final step in the HDB flat buying process is key collection. This is when you officially receive the keys to your new flat and become the legal owner.
Before key collection, you must pay the remaining balance of the purchase price. This is typically covered by your housing loan (HDB or bank).
Other fees may also be payable at key collection, such as:
Registration fees
Survey fees
Fire insurance premiums
HDB BTO, SBF, and Open Booking payment timeline
Purchasing an HDB flat involves various costs and payments at different stages of the process. This section provides a detailed breakdown of the payment timelines and associated expenses for each HDB flat acquisition method: Build-To-Order (BTO), Sales of Balance Flats (SBF), and Open Booking.
While there are some common fees across all methods, such as the application fee and Buyer’s Stamp Duty, the timing and specific amounts can vary. Therefore, it’s crucial to understand the nuances of each process to plan your finances effectively and ensure a smooth home-buying journey.
The following tables outline the typical payment timelines and costs for each flat type.
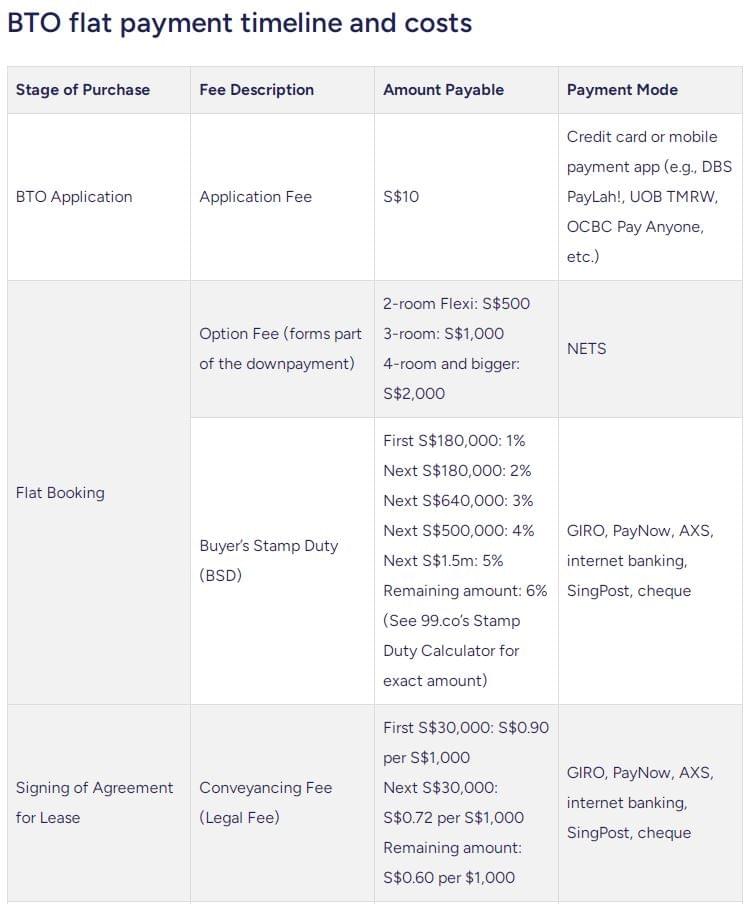
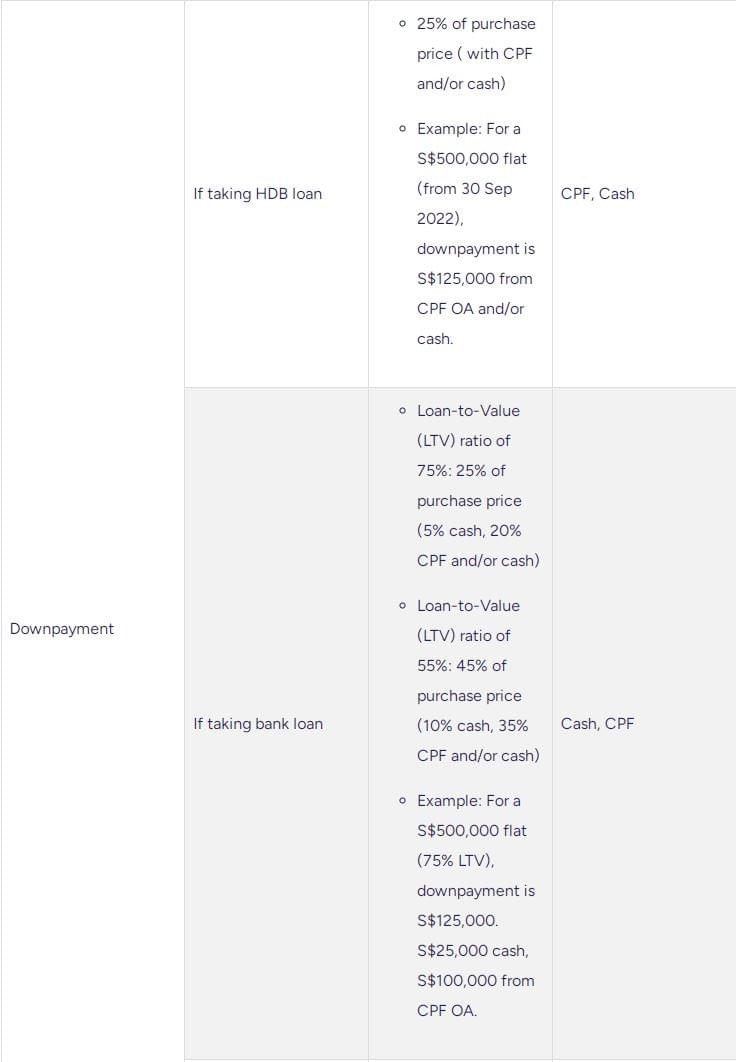
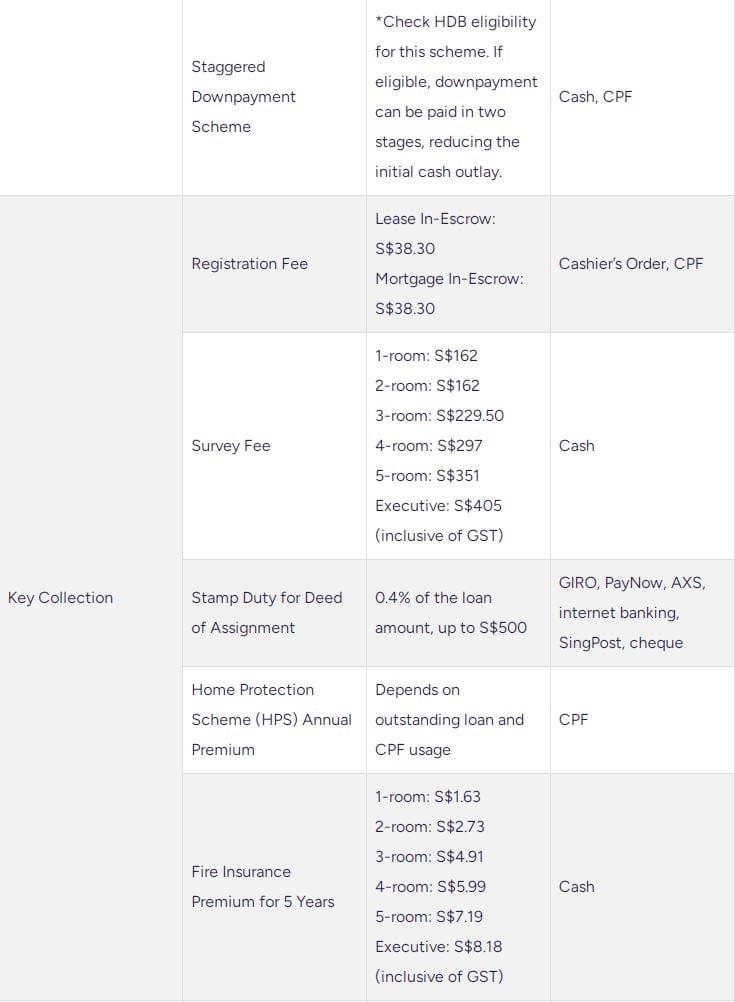
The BTO process involves a series of payments starting with a small application fee. The Option Fee secures the flat booking and forms part of the downpayment. Buyer’s Stamp Duty and legal fees are payable during the lease agreement signing.
The downpayment varies significantly depending on whether you take an HDB loan or a bank loan, and for bank loans, the Loan-to-Value (LTV) ratio is a factor. Key collection involves various smaller fees, with the remaining purchase price covered by the home loan. It’s crucial to understand the downpayment structure clearly.
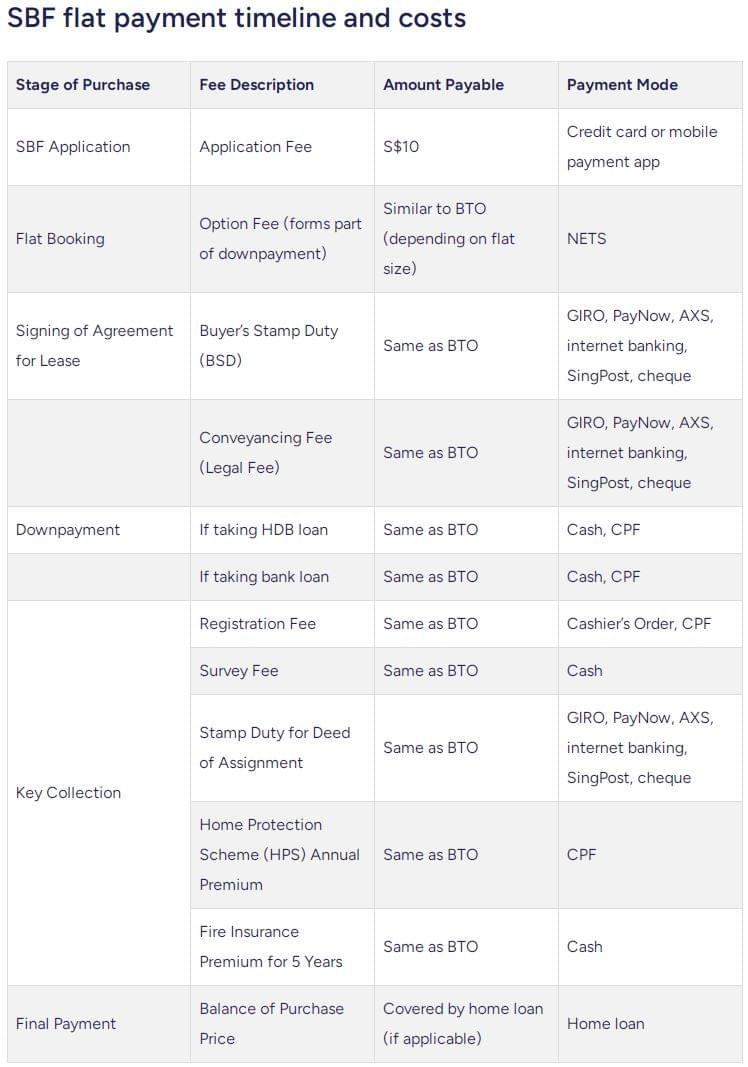
The payment timeline and costs for SBF flats largely mirror those of BTO flats. The key stages and fees, including the application fee, option fee, Buyer’s Stamp Duty, legal fees, downpayment structure (depending on loan source), and key collection fees, are generally the same.
This means that financial planning for SBF purchases can follow a similar approach to BTO.
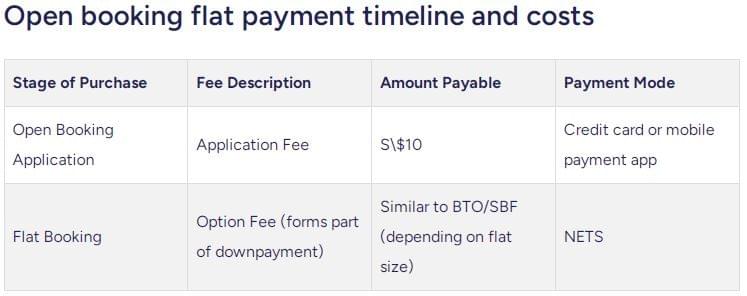
The payment structure for Open Booking flats aligns closely with BTO and SBF. The application fee, option fee, stamp duties, legal fees, downpayment arrangements, and key collection charges are generally consistent across all three methods.
This simplifies the financial planning process, regardless of the chosen flat acquisition route. However, due to the nature of Open Booking (immediate booking of available flats), the timeline between booking and key collection is typically shorter compared to BTO, which involves a construction period.
WE ARE READY TO ASSIST
We would love to help you in your property journey. Contact one of our TemasekClass consultants for a non-obligatory discussion.